

Understand and offset double burden
While operators of participating installations in the EU ETS 1 determine and report direct emissions from their installations (downstream approach), emissions within the National Emissions Trading System (nEHS) are determined indirectly via the quantities of fuel placed on the market (upstream approach). If a fuel within the scope of the nEHS is delivered to and used in an installation subject to the EU ETS 1, emissions from this fuel are covered by both systems.
Double burden due to fuel emissions from installations within the scope of the EU ETS 1 shall be prevented as far as possible using advance deduction pursuant to Section 7(5) BEHG in conjunction with Section 17 EBeV 2023. Where this is not possible, EU ETS 1 operators may offset double burdens that cannot be prevented in advance by subsequent offsetting in accordance with Section 11(2) in conjunction with the BEHG Double-Balancing Ordinance (BEDV). Storage quantities of fuels within the scope of the nEHS that are stored for later use in an EU ETS 1 installation are also deemed to be intended for use and thus double-burdened.
For stored fuel quantities for which subsequent offsetting was granted, the installation operator must provide proof of use in the following year in accordance with Section 6 (2) BEDV. We, the German Emissions Trading Authority (DEHSt), can extend the deadline for providing proof of use at the request of the installation operator.
Guidance (available in German only)
Basics of the application procedure
Applications for offsetting double burden must be submitted to us by July 31 of the calendar year following the accounting year in accordance with Section 8 (1) BEDV.
From the accounting year 2023 onwards, the application for offsetting double burden (Section 8 (3) BEDV) must include a certificate from a verification body (Section 21 (1) of the Greenhouse Gas Emissions Trading Act (TEHG)). The certificate must state that all factual information in the double burden application is free of material misstatements with reasonable certainty. The certificate is part of the FMS application in which the application is submitted. Since the accounting year 2023 onwards, there are fields for the verifiers. The information provided by the inspection body in these fields is regarded as a certificate (Section 8 (3) BEDV). The obligation to verify does not apply if the relevant emissions quantity for offsetting falls below 1,000 tons of CO2.
Operators within the EU ETS 1 must submit their applications for subsequent offsetting via the Virtual Post Office (VPS) using a qualified electronic signature. Please refer to our ‘Electronic communication’ page.
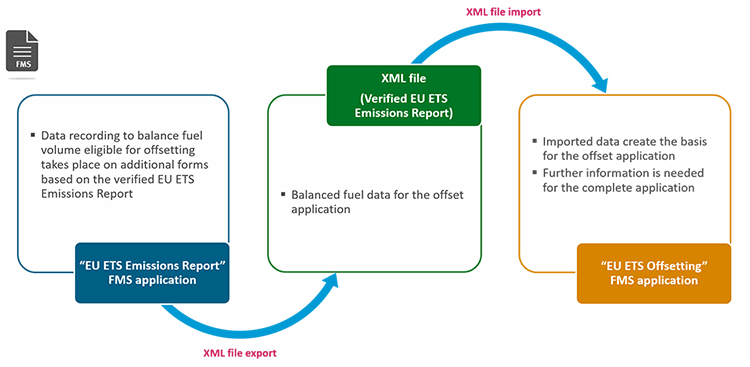
The application for subsequent offsetting can be created in a separate FMS application. You can use your existing access data to the FMS application for the EU ETS 1 emissions report for this purpose. The data for calculating the volume of fuel eligible for offsetting have to be recorded on the additional forms for the BEHG in the ‘EU ETS Emissions Report’ FMS application. Your verified EU ETS 1 emissions report is the basis for the recording. These forms also enable you to record the data for an advance deduction in accordance with Section 7(5) BEHG in conjunction with Section 17 EBeV 2023. The complete EU ETS 1 Emissions Report including the balanced fuel data from the additional forms for the BEHG is then exported from the ‘EU ETS Emissions Report’ FMS application and imported into the ‘EU ETS Offsetting’ FMS application. The imported data creates the basis for the offset application. In addition, further information is necessary for the complete application.
Further explanation on how to apply and fill in the FMS forms for the offset applications can be found in our ‘Guideline: Zusammenwirken EU-ETS und nEHS 2023 bis 2030’.
Guidance and assistance (available in German only)


Extension of the deadline for the provision of the evidence of use
Special rules apply if you have received financial compensation under the BEDV for quantities of fuel that were not used in the respective accounting year, but instead stored for later use. The compensation was granted in accordance with Section 9 of the BEDV, subject to the evidence of use being provided. This means that the compensated storage quantity must be used within the EU ETS 1 installation. If the compensated storage quantity is not used within the installation, the financial compensation for this quantity must be repaid.
The BEDV as the legal framework assumes that the compensated storage quantity of an accounting year will be used in the subsequent year and that evidence of use for this quantity will be provided with the EU ETS 1 emissions report for the subsequent year. An example can be found below. The payment notices for your compensation applications show the quantity of compensated storage in the table in the appendix („davon (…) nicht eingesetzte Menge“).
However, if the compensated fuel quantity stored in the accounting year cannot be used (or cannot be used in its entirety) in the following year for energy-related, technical or operational reasons and therefore the evidence of use cannot be provided (or cannot be provided in its entirety) with the EU ETS 1 emissions report for the following year, you can apply for an extension of the deadline for the provision of the evidence of use.
- With the application for the accounting year 2024 you can apply for an extension of the deadline for the provision of the evidence of use for fuel quantities that have already been compensated for but were stored in the accounting year 2024 and could not be used in the accounting year 2025. (Section 6 (2) No. 1 BEDV).
We can extend the deadline for the provision of the evidence of use by one year. The compensated fuels that were stored in the accounting year 2024 can then be used in 2026, and evidence of use must be provided with the EU ETS 1 emissions report for 2026, which is due by 31/03/2027.
Example
In this example fuels under the BEHG were procured for the EU ETS 1 installation in the accounting year 2024, but were not yet completely used. The total amount of fuel procured was claimed in the compensation application to be submitted by 31/07/2025.
The payment notice for the compensation for the accounting year 2024 therefore shows both the total eligible fuel quantity and the compensated fuel quantity that has been stored in the accounting year in the table in the appendix.
However, for technical reasons, the compensated but stored fuel quantity could not be used in the EU ETS 1 installation in 2025. This means that evidence of use cannot be provided in the EU ETS 1 emissions report for 2025 which is due to be submitted by 31/03/2026. In order to avoid having to repay the financial compensation that already has been granted, you can use the form linked below to apply for a one-year extension of the deadline for providing the evidence of use. If the application is justified the compensated but stored fuel quantity can be used in 2026 and its use can be verified in the EU ETS 1 emissions report 2026 by 31/03/2027.
Evaluations and reports
In accordance with Section 11 BEDV (BEHG Double Balancing Ordinance), we, the German Emissions Trading Authority at the Federal Environment Agency (DEHSt), as the competent authority, regularly report to the Federal Government on the main results of the offsetting procedure. Such a report has been submitted for the first time by 31/05/2024.
The reports are included in the evaluation of the Fuel Emissions Trading Act (BEHG) and thus in the Federal Government's progress reports in accordance with Section 23 BEHG. These progress reports can be found under the following link.
footnote